03 January 2015

Interest-paying money is not inflationary

(With credible fiscal policy, of course.)  Another interesting case, from JP Koning's Blog "Moneyness"

RBNZ decided to 'flood' the system with balances to make things more fluid. This involved conducting open market purchases that bloated the monetary base (comprised of currency plus deposits) from around NZ$6 billion in mid-2006 to just under NZ$14 billion by December of that year. See chart below. 
(Note that the RBNZ's problems began far before the credit crisis and were due entirely to the peculiar structure of the clearing system, not New Zealand's economy.)

Koning describes the lack of inflation as a result of the perceived "permanence" of the increased reserves. I think it comes from the fact that reserves pay interest -- as they do in New Zealand. Either way, the point is that banks and people are happy to sit on interest-paying money, in enormous quantities, just as they are on bonds.


The corresponding inflation and interest rates:

Source: Reserve Bank of New Zealand
http://www.rbnz.govt.nz/statistics/key_graphs/inflation/

Source: Reserve Bank of New Zealand
http://www.rbnz.govt.nz/statistics/key_graphs/90-day_rate/

More Cash and Zero Bound

In my last post I started thinking about how options other than currency enforce a zero bound. Imagine there is no more currency, and the Fed tries to impose -5% interest rates. You put in a dollar, you get out 95 cents. What other ways are there to guarantee that if you put in a dollar you get back a dollar? (In my last post, I also pointed out that in each case rules or laws could be changed, but that the magintude of the required changes was pretty big.)

 From Kenneth Garbade and Jamie McAndrews in a nice Liberty Street Economics blog post

  • Certified check. Go to the bank, tell the bank to write you a $10,000 certified check. Put it in your sock drawer. (More: "Certified checks, which are liabilities of the certifying banks rather than individual depositors, might become a popular means of payment, as well as an attractive store of value, because they can be made payable to order and can be endorsed to subsequent payees.")
Or, inspired by that: 


  • Don't cash checks. Every 90 days, call up, say you lost the check, ask them to reissue it. 
Clumsy. But as Ken and Jamie point out, it's very easy for a company to get started that does this, and offer fixed-value accounts to clients, beating the -5% at banks. Or, even in today's super-regulated environment, maybe banks could figure out to do this. After all, the Medici figured out in the 1400s to write offsetting bills of exchange to synthesize interest.

So, the project will mean changing the rules and laws governing checks, going back hundreds of years.

An earlier post by Todd Keister:

  • Money market mutual funds.
Currently money market funds promise fixed value, and pay positive interest.  They are not set up to charge negative interest, or to allow capital losses. Maybe they should -- I've argued for floating NAV -- but they don't. The Fed kept the 0.25% rate on reserves precisely so banks and money market funds didn't have to reinvent themselves in ways that allow capital losses or negative rates. 

Miles Kimball has also been writing in favor of negative nominal rates and thinking about the zero bound. One post is here. 

30 December 2014

Ruble Trouble

On Russia, the fall of the Ruble.

This is an interesting event on which to test out our various frameworks for thinking about macroeconomics and monetary economics.

Theories

There are three basic perspectives on exchange rates.

1. Multiple equilibria. Lots of words are used here, "speculative attacks," "sudden stops," "hot money," "self-confirming equilibria" "self-fulfilling prophecies" "contagion" and so on. Basically, the exchange rate can go up or down on the whims of traders. There is often some news sparking or coordinating the bust.  Some of the mechanism is like bank runs, pointing to "illiquidity" rather than "insolvency" as the basic problem.

This has been a dominant paradigm since the early 1990s. I've been a bit suspicious both on the nebulousness of the economics (lots of buzzwords are always a bad sign), and since the analysis seems a bit reverse engineered to justify capital controls, currency controls, (i.e. expropriation of middle-class savers and poor currency-holders), IMF rescues, and lots of nannying by self-important institutions and their advisers who will monitor "imbalances," "control" who can buy or sell what, and so forth. But models are models and facts are facts.

2. Monetary. Exchange rates come from monetary events, and primarily the actions of central banks. For example, much of the analysis of the dollar strengthening relative to euro and yen attributes it to the idea that the US Fed has stopped QE and will soon raise rates, while the ECB and Japan seem about to start QE and keep rates low.

3. Fiscal theory. Exchange rates come fundamentally from expectations of future fiscal balance of governments; whether the governments will be able and willing to pay off their debts. If people see inflation or default coming, they bail out of the currency, which sends the price of the currency down. Inflation follows; immediately in the price of traded goods, more slowly in others.

Craig Burnside, Marty Eichenbaum and Sergio Rebelo's sequence of papers on currency crises, starting with  JPE "Prospecitve Deficits and the Asian Currency Crisis" (ungated drafts here) was big in my thinking on these issues. They showed how each crisis involved a big claim on future government deficits.  Prices fall, banks get in trouble, governments will bail out banks, so governments will be in trouble.  Inflation lowers real salaries of government workers. And so on.

The "future" part is important. Earlier work on crises noticed that current debts or deficits were seldom large, governments in crises often had surprisingly large foreign currency reserves, and there were no signs of sudden monetary loosening.  This earlier absence of a cause problem had led to much of the multiple-equilibrium literature. But money is like stock, and its value today depends on future "fundamentals."

Monetary and fiscal views are related. The question really is whether the central bank can stop an inflation and currency collapse by force of will, or whether it will have to cave in to fiscal pressures.

Most basically, a currency, like any asset, has a "fundamental" value, like a present value of dividends; it may have a "liquidity" value, like money; and it may have a "sunspot" or "multiple equilibrium value." The question is, which component is really at work in an event like this one -- or, realistically, how much of each? The money and fiscal views also much more clearly bring the currency into the picture.

So, as I read the stories of Russia's troubles, I'm thinking about which broad category of ideas best helps me to digest it. You can guess which one I think fits best. Yes, everyone likes to read the paper and see how it proves they were right all along. But at least being able to do that is the first step.


On a second level, of course, there is the question whether prices and wages are sticky, whether "demand" or "supply" accounts for fluctuations, whether devaluations are great things to "stimulate" economies, and so forth.

Facts

1. Oil prices have gone down by half. Russia is a big exporter, and the Russian government gets a lot of revenue from oil exports, 45% by one media account.

2. The Ruble is collapsing. The graph below (from Bloomberg.com) shows the fall's slow slide, the sharp slide in early December, the big collapse two weeks ago, a rebound following various moves (more below) and a new sharp decline as I write.

5. Sanctions are biting. Sanctions cut off Russian businesses and banks from foreign financial markets. The big problem is not so much financing new investment, but that they now cannot roll over debts. (Sanctions seem to mean you can't borrow new money, but you still have to repay the old money.)

Paul Gregory, who among other things writes a blog about Russia, had a presicent Forbes article last August:
Russia, with its thin capital markets, obtains half of its capital abroad. If cut off from European, American, and Japanese capital cold turkey, Russia might be able to replace some of its losses from non-sanctioning countries, like China, but only partially and at a high price. [Many stories now in the news about Russia-China financial links.] 
Refinancing is a particularly harsh problem for Russia with its absence of rule of law. Lenders will lend only for short maturities. According to Russia’s central bank (CBR),  24 percent of the foreign debt of Russian banks and companies, or $157 billion, comes due in 2014 alone. Sanctions take the option of refinancing off the table.  Rosneft, the national oil company, has $15.9 billion maturing this year and $16.2 billion the next, for example, and it is only one of many companies in this fix. 
Remarkably, even unsanctioned Russian companies are frozen out of Western credit markets.  
5. There is a very interesting and quite murky debt situation, especially in banks.  Russian banks and businesses have a lot of foreign currency debt they can't repay or roll over.

The government debt/GDP ratio isn't that bad, and past deficits are not the trouble. Russia ran big trade surpluses, meaning there are foreign assets somewhere. But those may have all ended up as Russian owned London apartments and Swiss banks and not available to Russian banks and businesses.

Chain of events

The mid-December collapse happened around the Roseft bank story (below).  As I read it,  if markets sniff that foreign reserves are going to get spent fast to bail out favored cronies, then capital flight is on.  Fiscal theory and multiple equilibria paint similar pictures here. In a fiscal interpretation, news can come about how much of state assets are going to be used to support currency and government debt, and how much is going to line pockets of insiders. 

In addition, it must be on everyone's mind when capital controls are coming. Naturally, you want to get your money out ahead of capital controls. The fact that so much of our policy establishment now approves of capital controls means that controls are more likely, which means that crises are more likely. If capital controls were considered an awful step, like expropriating property or invading other countries, then people would be less likely to try to jump in advance of capital controls. 

The central bank responded by sharply raising interest rates to 18%, and interbank rates rose to 25%. That didn't seem to have much effect.  Long term rates went up sharply, all on their own. Inflation is already rising, with an official forecast of 11.5% for next year. We'll see what actually happens. 

Russian 10 year bond yields. Source: Financial Times

At this point, I was about to hit "send" on this post. Burnside Eichenbaum and Rebelo redux.  But then the Ruble bounced back.

On 12/25 Russia's finance minster declared the crisis "over" (WSJ "Russia Says Ruble Is Stable, but Economic Troubles Remain"). In addition to the interest rate increase, designed to make Rubles more attractive, factors cited included
exporters converted their dollar holdings to rubles to meet local tax payments due by the end of the month. [JC: and soaking up some Rubles] 
The ruble’s recovery this week was steered by the government’s order that major state companies sell foreign currencies, which applies to big exporters including Gazprom and Rosneft. Within the next two months, the companies will need to cut their foreign-currency holdings to levels of early October, which will fulfill the market demand for dollars and euros needed to repay foreign debt.
These are "voluntary" capital controls of the offer-you-can't-refuse sort. But none of these moves address the fundamental problems, so some frictions or multiple equilibrium story does come to mind first. The articles also mention thin markets around holidays. It's easier to move prices in thin markets.

But then as of the end of the year, the Ruble is heading down again, which looks to me like fundamentals taking over.

On 12/26 "Ruble’s Recovery Runs Out of Steam'' says the Wall Street Journal. Interestingly, Russian Finance Minister Siluanov has become a fiscal theorist when it comes to steps to help the Ruble.
 Mr. Siluanov admitted that Russia will need to adapt its budgets to “new economic realities.” 
The minister said that Russia will need to reassess its military spending amid slowing economic growth and reduced access to global capital markets as falling oil prices have hit the domestic economy hard. 
...“The budget structure is extremely ineffective. It needs to be changed in the conditions when we have limited access to new sources of income,” Mr. Siluanov said.
The macroeconomic stories are interesting as well.  WSJ echoed the interest-rate-centric view of macroeconomic effects :
...the sharp interest-rate increase that the central bank imposed last week to stem the ruble’s slide, along with widening problems in the banking sector, has darkened the outlook for Russia’s economy dramatically.
Really? Of all the problems in Russia's economy too high interest rates and lack of "demand" are the most important?  Also, we will see whether 18% turns out to be a low or a high real interest rate.

Devaluation and inflation are  supposed to boost economies because prices and wages are sticky. There were great news stories about a crush to buy Ipads at the Apple store in Moscow, and Apple eventually closing it down because they couldn't keep up with currency changes. Ipads seem to be the new Krugerrands. So, there's a little bit of sticky price demand, I guess. Lasting maybe a day.

Some additional readings

Falling oil, rising cucumber prices: how much trouble is Russia in?

Recent calculations show that Russia needs oil to stick to around $105 a barrel for its budget to break-even. .
Russia’s external debt amounted to $731bn in June 2014. 74% of this is denominated in foreign currency, meaning that the depreciation of the rouble makes it more expensive to repay... $35bn of debts are due in December alone.
The largest component of debt is attributable to banks and other non-government sectors, which together owe more than $650bn to foreign lenders, 17% of which is short-term, and much of which (46%) is attributable to state-owned banks and enterprises.
Sanctions too are starting to bite. Companies directly under western sanctions account for about 60% of the total debt due by the end of 2015 (£).
While most of these companies are (for now) relatively cash rich, the fact that many are sanctioned from raising finance means that they cannot simply roll over debt by borrowing externally, and need to instead buy dollars in the market. There also appears to be growing evidence (£) of concerned western banks and financial institutions refusing to finance even those Russian companies that are not on the blacklist.
It is worth keeping in mind at this point that while not being state-run, private companies are often merely quasi-sovereign in Russia, and ownership structures are rather fluid and can change quite rapidly - the potential weight of debt on government finances goes beyond only state-run companies.
... banks alone have $192bn external debt (about 10% of GDP), up from $170bn in 2008, and from $18bn in 1998....The key point here is that Russia’s banks have few dollar assets to set against their dollar debts.
As an example of some of this debt issues, lies the Rosenft loan: Leonid Bershinsky (Dec 15)
Russia's state-owned oil company, Rosneft, raised 625 billion rubles ($10.8 billion at that day's exchange rate) with a bond issue that had a lower yield than Russian government bonds of similar maturity. The Central Bank quickly added the bonds to the list of securities it would accept as collateral from banks seeking liquidity. The deal was opaque,...

Central Bank technocrats have been worried that the government would force them to print rubles for the direct funding of industries, primarily the military industrial complex and the state companies run by Putin friends. The Central Bank's obvious complicity in the Rosneft deal means the pressure is on, and the Central Bank is caving.
Andrew Kramer at the New York Times (dec 16)
He [Putin] faces a particularly delicate dance with Russian companies, which are under significant financing strains. Russian corporations and banks are scheduled to repay $30 billion in foreign loans this month.

And next year, about $130 billion will be due. There is no obvious source for these hard currency payments other than the central bank, whose credibility is now being called into question.

Rosneft, for example, had been clamoring for months for a government bailout to refinance debt the company ran up while making acquisitions when oil prices were high. Because of sanctions, those loans cannot be rolled over with Western banks. Debt payments are coming due later this month.

... With the oil giant in a bind, the central bank ruled that it would accept Rosneft bonds held by commercial banks as collateral for loans.

Rosneft issued 625 billion rubles about $10.9 billion at the exchange rate at the time, in new bonds on Friday. The identities of the buyers were not publicly disclosed, but analysts say that large state banks bought the issue.

When these banks deposit the bonds with the central bank in exchange for loans, Rosneft will have been financed, in effect, with an emission of rubles from the central bank. The deal roiled the ruble on Monday, according to analysts.

The reason for Monday’s currency crash is “well known,” Boris Y. Nemtsov, a former deputy prime minister who is now in the political opposition, wrote on his Facebook page. “The central bank started the printing press to help the Sechin-Putin business, and gave Rosneft 625 billion newly printed rubles. The money immediately appeared on the currency market, and the rate collapsed.” Rosneft, in a statement, denied it had exchanged funds raised from the bonds for hard currency.
Holman Jenkins at Wall Street Journal
Which brings us to Rosneft . This week’s sharp plunge in the ruble was less linked to oil than to a mysterious “bond offering” by the state-controlled Russian oil giant, indirectly financed by Russia’s central bank. 
On Monday, Rosneft felt obliged to issue a one-paragraph statement denying that the ruble proceeds would be used to buy foreign currencies to meet Rosneft’s hefty foreign-debt repayments.
On Why the Ruble is Collapsing,
The value of the ruble dropped as much as 19 percent in the last 24 hours, the worst single-day drop for the ruble in 16 years. Now Russians are reportedly bum-rushing malls to swap cash for washing machines, TVs, or laptops—anything that seems as if it might hold value better than paper money, whose worth is evaporating in real time....
Russia's Central Bank has been trying to fight this trend, first by using its stockpile of foreign currencies to go out into the market and buy rubles, hoping to prop up the price. Then, early in the morning on Tuesday in Moscow, the Central Bank announced a gigantic interest rate increase. The idea is that if you offer people higher interest rates, they're more likely to keep their money in rubles.
Neither move has worked. 
Neil Irwin at New York Times
But interest rate increases aren’t free. Higher interest rates are sure to choke off any chance for growth in a Russian economy that is already reeling from falling oil prices.
Financial Times
The main reseller of Apple in Moscow, re:Store, saw sales two to three times higher than normal at one central branch, according to a salesman, reports Jack Farchy in Moscow.
Another store visited by the FT had sold out of iPhone 6's and iPad Airs entirely by Tuesday night (see first picture).

Marginal revolution commentary and links.

A nice graph from Bloomberg's Henry Meyer and Ilya Arkhipov capturing some of the events:


28 December 2014

Paulina Peavy Interview on Long John Nebel Radio Show 1958

The intelligence speaking through Paulina Peavy said: " . . . we are using her exactly as you use your microphone.  We are beings existing in a world of too high frequency for your comprehension."  (This photo of  'Pauline Peavy' is from the 1971 book The Age of Flying Saucers by Paris Flammonde.)
  
 
Upon listening to a commercial audio CD with MP3 files of 1950s radio shows hosted by 'Long John Nebel,' the most intriguing guest was described in the show descriptions with her name misspelled: "A Mrs. Pievey went into a trance and communicated with spirits."  The expression 'channeler' wasn't a commonly known term at the time so there was some difficulty for Nebel when he attempted to explain her circumstances.  Joining Nebel in asking questions of the interview guests were a couple of "The Party Line" recurring panelists.

During this January 1958 broadcast, the predominant interview subject was 'the mystic barber' of Brooklyn, Andy Sinatra, who wore a metal headband and professed to have experience with astral projection.  At one point Sinatra said: "The public likes to laugh and wants a little comedy once in a while . . . I'm putting on a show . . . It's based on certain real things . . . This [astral projection] is my own experience."

When Nebel first spoke about the possibility of talking with Peavy later in the broadcast, he mentioned that she had brought with her one painting and a number of photos of other paintings plus some masks.  He said: "And this lady goes into a trance.  She goes to different dimensions and when she's in these different dimensions she paints these pictures.  Now I know nothing about the trance state or the other dimensions but the pictures are beautiful.  There's no two ways about that."

Approximately two hours later, Nebel introduced Paulina Peavy as "a lady who goes into a trance and during the time that she's in the trance she receives inspirations to paint.  Now I possibly have not phrased this right but this is about all I know at the moment.  I can say this to you though — that Pauline Peavy is an artist, inventor, designer, sculptor, poet, writer and lecturer."  Nebel continued:

And she was born in Colorado City.  She lived most of her adult life on the West Coast.  And she has received degrees in art and education from leading colleges and schools as well as honors and awards in art and architecture.  Possibly some of you people have seen her work at the various art galleries.  Now, Miss Peavy is sitting to my right.  To her left opposite me is Dave Bell.  To my left, opposite Miss Peavy is Charles Leedham.  Miss Peavy has a very, very unusual mask on.  To describe the mask, I would say that it looks like a base color of chartreuse with gray stripes — sort of charcoal gray stripes running through it diagonally.  There are many fancy trimmings around it.  It's a very large mask that covers at least three-quarters of her face.  There are pearls on both sides of the mask and a number of pieces of metal.  I would say it's a very, very attractive and a very beautiful work of art as far as masks are concerned.  And she tells us that it's important that she wears this mask during the time that she's in the trance state.

Nebel began the interview by asking her when did she first realize that she could go into a trance.   Peavy showed none of Sinatra's jocularity as she answered questions and this sensibility was consistent throughout the interview.  She replied: "At least twenty-five years ago.  I heard voices — very strange voices coming through me."  Nebel said, "Coming through you?"  She replied, "Yes — startled me a very great deal although I had been investigating the mystery of my paintings, which started coming twenty-five years ago."  As Nebel began asking her a new question, Peavy began loudly grunting.  She attempted to explain while going in and out of trance.

Now — now — I explain — when — when such power moves in, the strange sounds are caused by the power taking over.  You see Paulina squirming about because we are putting into her being high voltage and in order to receive us and maintain herself, she has had to build up her electrodes to meet our high voltage.  (change in voice tone)  Well that's the way they come in.  And then they release me and then apparently I talk.

Nebel asked her, "How do you feel when you're in a trance, Pauline?"

Well, I feel very exhilarated and (change in voice tone) now, as you will see, this is not the voice of Paulina for we have not released her entirely.  Although we have prepared her that when we come through we are using her exactly as you use your microphone.  We are beings existing in a world of too high frequency for your comprehension.  And we need to lower our frequency by this manner that our thought will be audible to you.  We use Paulina who uses us.  Together, we have painted many thousands of paintings in her — several hundred, probably near a thousand for the purpose of introducing ourselves to you in the way that we desire to be introduced.  For you have many ideas regarding us that are your ideas and they are not our reality.  And as we come to you in many ways and you call us 'flying saucers,' 'space men,' 'Venusians,' and other of your names we need to introduce ourselves in our language.  And our language is not a babble tongue for we communicate with each other in our world by sending or radiographing, as you would say, pictures.  (change in voice tone)  I think the pause is for questions.

Peavy went on to explain:

The beings that I entertain are universal beings who do not render (change in voice tone) individual personalities as you do in your world.  We are universal beings.  We do not place upon ourselves labels as do you to call ourselves John Doe forever for we now, hold your hats — for we have found perpetuity of life.  And it would be very droll if we called ourselves Paulina Peavy for the rest — from now on.  Therefore, we come and many times when you hear one voice you hear a multitude of us.  For we are in a world whereby we have thoughts simultaneously with uncountable legions of us.  We do not give Paulina personal names for us.  She has a name which is her name when she speaks to us.  We do not use your names in our world. 

There was another pause and Dave Bell asked, "Are the people in this world like we are?"

We are your elders.  We ages ago were like you, as you.  We have progressed by many eons of time beyond your station and now we exist as a perfected—you would say—seed.  When you see us and we are able to reduce our high frequency waves to come into your sight in your skies; and you see us as flying saucers, we are showing you our planetary form for we are a single cell with one eye.  The original eye.  Out of that single cell we mutate into creature form as you take your birth.

Dave Bell said, "Then the explanation of the flying saucers is an attempt of these people to enter into our world?"

We have never departed you and your world.  And the world is not as you think you see it with your two outer eyes.  You might say the world, id (or "ID"), an atomic nature of matter.  We do not see skies like you see skies.  We see into the eye of the atom.  Even the eye of the atom that you smash.  And you know that when you smash an atom you see volumes of infinity emerging from that microscopic eye.  We indwell, ourselves, our eye — we are interspacial beings coming out, emerging or slowing up our molecular rate that you might perceive us. 

Nebel asked Dave to give her a glass of water and permit her to rest.  Before Peavy resumed her participation in the broadcast, Andy Sinatra was interviewed further.  At one point Nebel asked Sinatra to "do a little spacetalk for us."  Sinatra cooperated and the syllables sounded to Leedham as being like American Indian languages.  Nebel and his panelists were soon wisecracking and convulsing with laughter.  At one point Andy mentioned having been with Peavy when he experimented with her guide: "He said to us that if there was nine people there . . . he would make himself visible.  But we didn't have nine people that were in harmonious vibration."  Later, Nebel directed Peavy to ask her spirit mentor to translate the space language that would be given by 'the mystic barber.'  After Nebel stated that Peavy had her mask on again and he reintroduced her to the listening audience, she began groaning and there was a resumption of the trance communication.

We travel in space from a point of time to a point of time, which tells you absolutely nothing, meaning that we are almost as bewildered as you about space travel.  (pause)  We make our food by the power of thought.  The best that we can explain to you is that we counteract the disintegration of atoms in space.  And our food is wholly made by the power of thought as we travel in our state of electronic fluidity.  (pause)  You have a saying that your home is where you hang your hat.  Our home is where we think it is.  As we know no boundaries like you, we move through walls—your walls—faster than the speed of light like your radio beams move through obstacles that are obstacles only to you.  (pause and then the voice makes sounds similar to Andy's chanting)  Oh ho ho ho ho — ho ho ho, yes Andy, ha aa ah — yeah ha ha.  We did visit you in behalf of our work.  As you saw it.   When we thank you for your currupo — cooperation in our bequest.  For we asked you not to tamper with Paulina and us in our connection and you so graciously acceded.  Time writes a heavy hand for seers.  We need all the cooperation from your men of science that we can get.  We need to work with you to make this matter understandable which means scientific — this matter of the sensitives of your world who have been contacting us throughout the ages and who have not been understood.  We see no more burning of your Joan of Arcs but we do see ridicule by those who are not enlightened regarding this relay system.  A voice projection — astro-projection as you call it.  Andrew, when we take you to a planet called the moon, we take you to a solar system within yourself in correlation to the outer, as you call, solar system.  (pause)  We have helped you make your headband.  We have given you all the secrets for such a headband we placed upon Paulina twenty years ago — an unseen magnetic headband.  We placed a magnetic field upon her head and upon her right ear which has been there for twenty-fi(ve) — twenty years.  And longer but twenty years to her knowledge.  Permitting us to motivate through her vocaluary gland with her ego still conscious.  Ha ha ha ha ha ha — (utterances like Indian chanting) — We are so elated that such a program as this is possible in your age.  We are so happy to find your open-minded attitude toward our contact with you to the state whereby you can broadcast our voice — our voices.   Andrew, the bread of life is life.  Your questions.  (pause then change of voice tone)  If you wish to ask about their world — now, you see, I — when I think I'm out of the trance (change of voice tone) I'm not.  I mean that their voices and mine sometime are simultaneous. 

Nebel asked, "I wonder if you could — could we get any information about Sputnik?  The Earth satellite."

We regret to say that matter made by the hand cannot sustain by safe travel.  We know that you gain great knowledges.  What a fantastic thing to send — a body hurtling out into an orbit.  How wonderful if you could gather together your admiration for scientific achievement forgetting your desire to blow somebody to bits.  We ask you to please change the subject.  We are too adamant.  You would not like it were we to go all out.

Charles Leedham stated, "You would prefer questions on another subject, is that it?"

Questions about our existence we shall ask.

Nebel then said, "I think in all fairness, Charles, I've been informed by one of the — Miss Peavy's friends who happen to be up here at the present time that she's under terrific strain and that we shouldn't talk any more to the spirit voice — permit Miss Peavy to relax."  Then Andy Sinatra was interviewed once more.  

This January 1958 broadcast recording is now available for listening on You Tube.

This week I conducted an Internet search to see what other information is available about Pauline/Paulina Peavy (1901-1999).  In addition to a short biography at AskART citing Artists in California 1786-1940 by Edan Hughes, there is a patent description for Beneficial skin and tissue cover device, Trademark data, and artist file data for holdings at the Frick Collection and Frick Art Reference Library.  

Two noteworthy articles were found.  In an archive.org text entitled Architect and Engineer with the date of January 1944, an article was found with the headline "California Artist's Work Reviewed by 'Art Digest.'"  There was commentary about the "astonishing paintings" by "Mrs. Pauline Peavy of California."  A reviewer with the initials 'M.R.' compared her work with Salvador Dali's and wrote: "The keynote of the exhibition of 59 paintings, the work of the last seven years, is a 14-foot long panel of 'The Last Supper.'  In colors like Byzantine enamels, she has painted the figure of Christ as compassionate, of pure thought and absolute justice and the disciples as representing various aspects of our character."

An article published in the Brooklyn Eagle on November 25, 1946 included a photograph of Peavy and quoted Peavy about how life on Earth would improve once the secret of atomic energy is discovered: "We should then be able to make use of atomic energy to multiply, rather than use its power to disintegrate as the atomic bomb does now."
 

26 December 2014

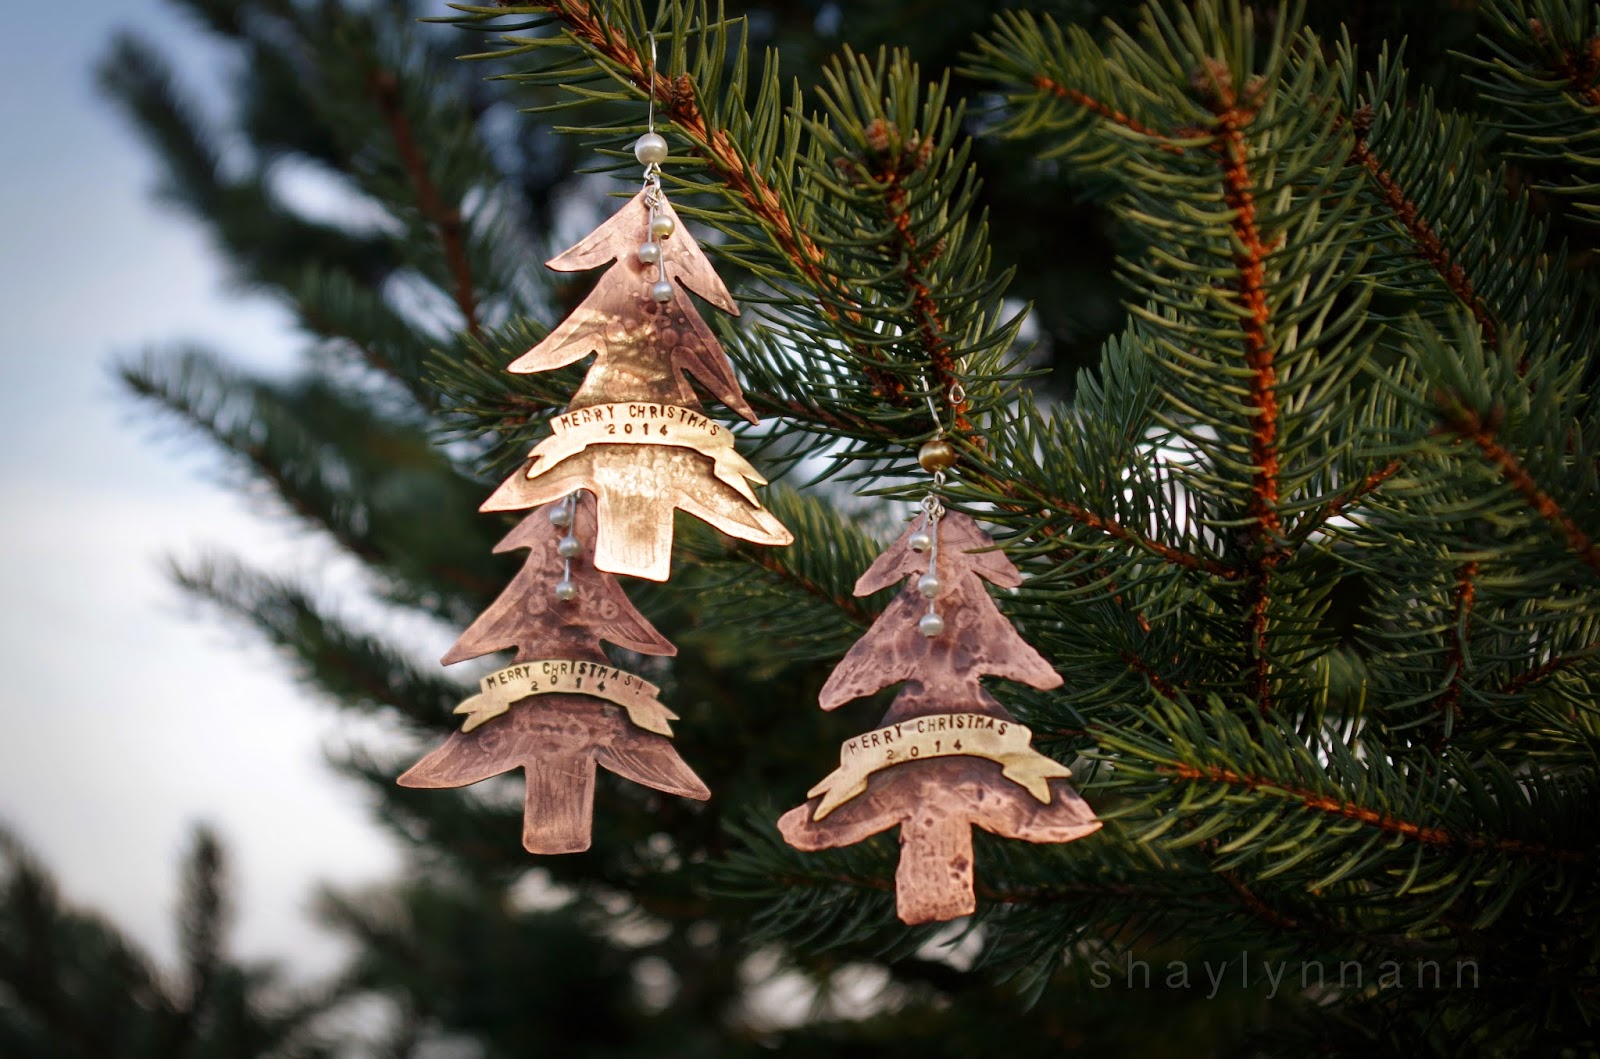
Merry Christmas! | Copper Tannenbaum Ornaments


I write this curled up on the couch, sipping hot holiday spice tea (compliments of Santa), with the Christmas tree lighting the room. Gathering Blue by Lois Lowry is on the couch beside me, and the rest of my family is asleep. This Christmas was beautiful; while we officially began our celebration with Mass on Christmas Eve, we really began Christmas break a few days ago when both my brother and I returned from college and my dad took off work.

A tornado of little children tore through our living room on a mission to create messes. The remainders of a long day are strewn every which way. Instrumental Christmas music is playing and there is the promise of a day of unwinding and cleaning before more family events.

I hope that all of you have had beautiful Christmases, full of family and friends and crazy weird traditions!

My Christmas gift, both to myself and from my parents, is a TORCH!

That's right-- I now have a propane/oxygen little torch that can heat up to, you know, just a couple thousand degrees. I also now have a crockpot labeled "poison" (for heating up pickle, a substance which cleans metal when it is discolored from heat and flux). I can now solder!!!!!

My little sister and I test-ran the torch, my metal stamping set, and my miniature hacksaw to create  these Christmas gifts! These Christmas tree ornaments are handmade from copper and brass.


My eleven-year-old sister cut out the brass banners and stamped the numbers on them. (Can you believe it?!) She requested to be my apprentice over Christmas break, and while she sometimes makes things take forever, on the whole she's actually been very helpful and is becoming quite skilled.


The trees are hand-cut from copper which I etched and then drilled.

Normally I would etch copper with ferric chloride, but I recently ran out and discovered that buying more would be quite expensive. I was using etchant from my grandpa's old PCB etchant kit before. So, I did some research, and my dad and I mixed up an acid bath that is essentially a cupric chloride --> cuprous chloride etchant. So now I also have an apple juice container with bright yellow duct tape that shouts "DANGER: Poison" in thick Sharpie!

Unfortunately I had already etched quite a few pieces of copper by the time I got around to etching the trees and didn't properly reconstitute the solution, so the etch was not very deep. That or my resist came off. I'm not 100% sure what went wrong.

I think that the idea of little handdrawn ornaments comes through nonetheless.

I then soldered the stamped brass banner onto the tree (THAT was a process because I had a difficult time getting the whole copper tree up to temperature).


As you can see, my sister and I had a lot of stamping to do. Each letter is hammered in by hand.

At the very end of the process, we submerged the ornaments in a Liver of Sulfur solution, sanded it down, and sealed the pieces with a spray expoy resin.

Then, we strung glass pearls onto headpins, and made a pearled tree hook from an eye pin!


I am so fascinated by all of these new metalwork processes that I am discovering. :)

My grandparents gifted me a dip pen for calligraphy (and for my upcoming illustration class) so I'll be experimenting with that, too! I've been using a worn-out fountain pen with three nibs since I was eleven or twelve.

But that is not now. Now is time for bed, and visions of sugar plum fairies-- it's almost surreally peaceful tonight.

22 December 2014

Inequality at WSJ -- the oped

This is a Wall Street Journal oped on inequality. With 30 days passed, I can post it here. It's a much edited version of my evolving "Why and How we Care About Inequality" essay.


What the ‘Inequality’ Warriors Really Want

Progressives decry inequality as the world’s most pressing economic problem. In its name, they urge much greater income and wealth taxation, especially of the reviled top 1% of earners, along with more government spending and controls—higher minimum wages, “living” wages, comparable worth directives, CEO pay caps, etc.

Inequality may be a symptom of economic problems. But why is inequality itself an economic problem? If some get rich and others get richer, who cares? If we all become poor equally, is that not a problem? Why not fix policies and problems that make it harder to earn more?


Yes, the reported taxable income and wealth earned by the top 1% may have grown faster than for the rest. This could be good inequality—entrepreneurs start companies, develop new products and services, and get rich from a tiny fraction of the social benefit. Or it could be bad inequality—crony capitalists who get rich by exploiting favors from government. Most U.S. billionaires are entrepreneurs from modest backgrounds, operating in competitive new industries, suggesting the former.

But there are many other kinds and sources of inequality. The returns to skill have increased. People who can use or program computers, do math or run organizations have enjoyed relative wage increases. But why don’t others observe these returns, get skills and compete away the skill premium? A big reason: awful public schools dominated by teachers unions, which leave kids unprepared even to enter college. Limits on high-skill immigration also raise the skill premium.

Americans stuck in a cycle of terrible early-child experiences, substance abuse, broken families, unemployment and criminality represent a different source of inequality. Their problems have proven immune to floods of government money. And government programs and drug laws are arguably part of the problem.

These problems, and many like them, have nothing to do with a rise in top 1% incomes and wealth.

Recognizing, I think, this logic, inequality warriors go on to argue that inequality is a problem because it causes other social or economic ills. A recent Standard & Poor’s report sums up some of these assertions: “As income inequality increased before the [2008 financial] crisis, less affluent households took on more and more debt to keep up—or, in this case, catch up—with the Joneses. ” In a 2011 Vanity Fair article, Columbia University economist Joe Stiglitz wrote that inequality causes a “lifestyle effect . . . people outside the top 1 percent increasingly live beyond their means.’’ He called it “trickle-down behaviorism.”

I see. A fry cook in Fresno hears that more hedge-fund managers are flying in private jets. So he buys a pickup he can’t afford. They are saying that we must tax away wealth to encourage thrift in the lower classes.

Here’s another claim: Inequality is a problem because rich people save too much. So, by transferring money from rich to poor, we can increase overall consumption and escape “secular stagnation.”

I see. Now we need to forcibly transfer wealth to solve our deep problem of national thriftiness.

You can see in these examples that the arguments are made up to justify a pre-existing answer. If these were really the problems to be solved, each has much more natural solutions.

Is eliminating the rich, to eliminate envy of their lifestyle, really the best way to stimulate savings? Might not, say, fixing the large taxation of savings in means-tested social programs make some sense? If lifestyle envy really is the mechanism, would it not be more effective to ban “Keeping Up With the Kardashians”?

If we redistribute because lack of Keynesian “spending” causes “secular stagnation”—a big if—then we should transfer money from all the thrifty, even poor, to all the big spenders, especially the McMansion owners with new Teslas and maxed-out credit cards. Is that an offensive policy? Yes. Well, maybe this wasn’t about “spending” after all.

There is a lot of fashionable talk about “redistribution” that’s not really the agenda. Even sky-high income and wealth taxes would not raise much revenue for very long, and any revenue is likely to fund government programs, not checks to the needy. Most inequality warriors, including President Obama, forthrightly advocate taxation to level incomes in the name of “fairness,” even if those taxes raise little or no revenue.

When you get past this kind of balderdash, most inequality warriors get down to the real problem they see: money and politics. They think money is corrupting politics, and they want to take away the money to purify the politics. As Berkeley economist Emmanuel Saez wrote for his 2013 Arrow lecture at Stanford University: “top income shares matter” because the “surge in top incomes gives top earners more ability to influence [the] political process.”

A critique of rent-seeking and political cronyism is well taken, and echoes from the left to libertarians. But if abuse of government power is the problem, increasing government power is a most unlikely solution.

If we increase the top federal income-tax rate to 90%, will that not just dramatically increase the demand for lawyers, lobbyists, loopholes, connections, favors and special deals? Inequality warriors think not. Mr. Stiglitz, for example, writes that “wealth is a main determinant of power.” If the state grabs the wealth, even if fairly earned, then the state can benevolently exercise its power on behalf of the common person.

No. Cronyism results when power determines wealth. Government power inevitably invites the trade of regulatory favors for political support. We limit rent-seeking by limiting the government’s ability to hand out goodies.

So when all is said and done, the inequality warriors want the government to confiscate wealth and control incomes so that wealthy individuals cannot influence politics in directions they don’t like. Koch brothers, no. Public-employee unions, yes. This goal, at least, makes perfect logical sense. And it is truly scary.

Prosperity should be our goal. And the secrets of prosperity are simple and old-fashioned: property rights, rule of law, economic and political freedom. A limited government providing competent institutions. Confiscatory taxation and extensive government control of incomes are not on the list.

Mr. Cochrane is a professor of finance at the University of Chicago Booth School of Business, a senior fellow at the Hoover Institution, and an adjunct scholar at the Cato Institute.

Autopsy

Autopsy for Keynesian Economics. (I don't get to pick the titles BTW) A Wall Street Journal Oped. I'm trying for something cheery at Christmas, and a response to the many recent opeds that ISLM is just great and winning the battle of ideas.  As usual, the whole thing will be here in a month.
This year the tide changed in the economy. Growth seems finally to be returning. The tide also changed in economic ideas. The brief resurgence of traditional Keynesian ideas is washing away from the world of economic policy.
No government is remotely likely to spend trillions of dollars or euros in the name of “stimulus,” financed by blowout borrowing. The euro is intact: Even the Greeks and Italians, after six years of advice that their problems can be solved with one more devaluation and inflation, are sticking with the euro and addressing—however slowly—structural “supply” problems instead.
Read more at WSJ...

Update: Hoover has an ungated version here;  Cato has an ungated version here.

  • bgbgb